Most Kenyans do not buy a car with cash. Instead, they use bank asset finance, a SACCO loan or, sometimes, a logbook loan. Then they need comprehensive insurance from day one, because every lender insists on it. This guide explains both, in plain language, for imported cars.
We cover how asset finance works for direct imports from Japan and the UK, what banks ask for, how logbook loans compare, and what drives insurance premiums for a Range Rover, a Toyota V8, a G-Wagon, a Harrier, a CX-5 or a Prado. In addition, we explain how Elisa Motors supports your financing with the right documents.
How car asset finance works in Kenya
Asset finance is a loan secured on the car itself. You pay a deposit, the bank pays the balance, and you repay monthly over an agreed term. Until you finish paying, the bank is joint owner on the NTSA logbook. Once you clear the loan, the bank releases its interest and the logbook moves to your name alone.
Most major Kenyan banks offer it, including KCB, NCBA (which absorbed the former NIC Bank), Equity, Co-operative Bank, Stanbic, Absa, I&M, DTB and Family Bank. SACCOs and some microfinance lenders also finance cars. Terms vary, so compare at least three offers.
What banks usually ask for
Requirements differ by lender. However, you can expect most of the following:
Deposit. Most banks ask for a deposit, often a fifth or more of the car's value. Older or high-value cars may need more. Term. Repayment periods commonly run up to four or five years. Car age. Many lenders cap the car's age at the end of the loan. Therefore, a younger import is easier to finance.
Documents. You will need ID, KRA PIN, bank statements, payslips or business records, and a pro-forma invoice or sale agreement. Valuation. The bank sends the car for valuation by an approved valuer. Insurance and tracking. The bank requires comprehensive insurance and an approved tracking device for the life of the loan.
Financing a direct import from Japan or the UK
Financing an import is slightly different from financing a car already in Kenya. Some banks pay the importer once the car is cleared and ready for registration. Others can release funds earlier against a pro-forma invoice and shipping documents. Ask your bank which approach it uses before you commit.
Here is a common flow. First, you pay your deposit to the importer. Next, the importer buys and ships the car. Then, when the car lands and clears, the bank pays the balance and is joint-registered on the logbook. Finally, the car is handed over with tracking and insurance in place.
Elisa Motors provides a detailed pro-forma invoice, the car's specs, photos and shipping documents. As a result, your bank has everything it needs for approval and valuation. Read our import guide for the full timeline.
Financing a luxury SUV: Range Rover, V8 and G-Wagon
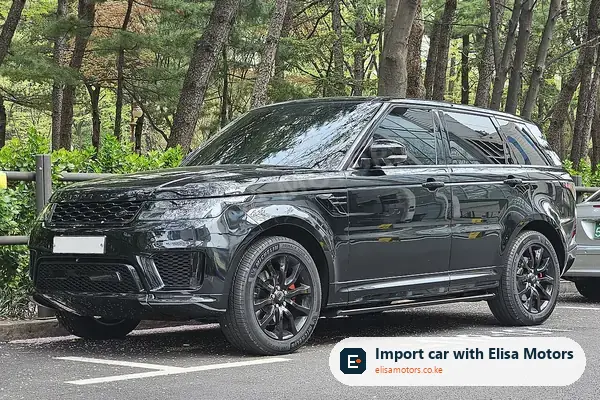
Buy a Range Rover with bank finance in Kenya
A Range Rover Sport HSE SDV6 lands at about KES 9M – 11M. Banks finance Range Rovers readily. However, some valuers are cautious about older units because of repair costs. Consequently, a younger, full-history import usually gets better terms.
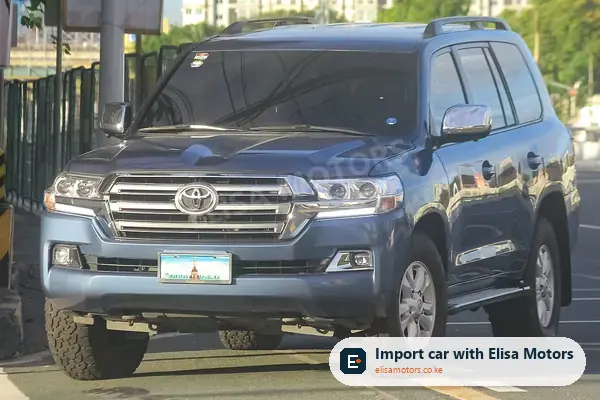
Asset finance for a Toyota V8
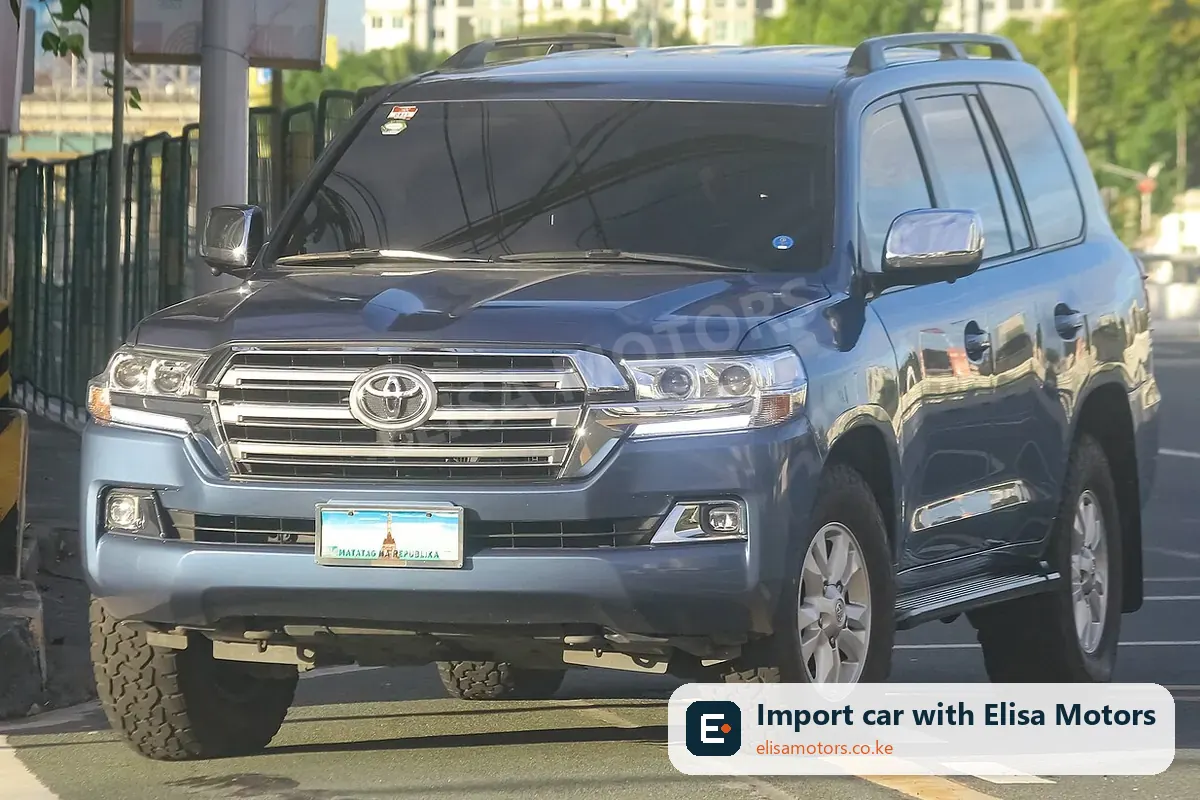
The Land Cruiser is a favourite with lenders because it holds its value so well. A Land Cruiser 200 VX lands at about KES 13M – 16M. Bank finance for a used V8 is common, and strong resale means valuations tend to be firm.
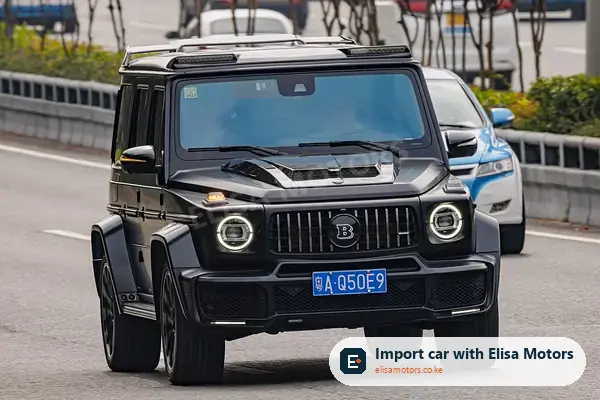
Buy a Mercedes G-Class with a bank loan
A G400d lands at about KES 20M – 24M and a G63 AMG at KES 28M – 36M. At that level, banks look closely at income and may ask for a larger deposit. Moreover, insurers may require extra security measures.
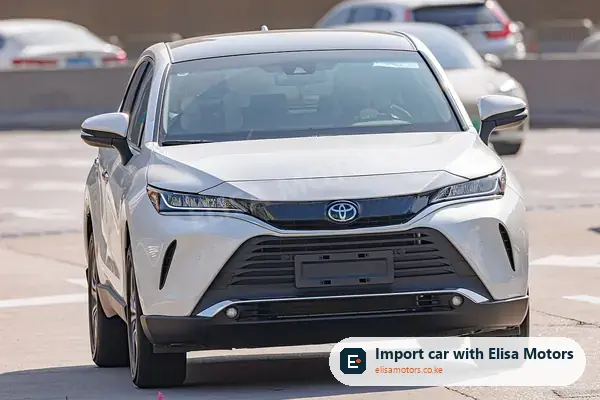
Financing a Harrier, CX-5 or Prado
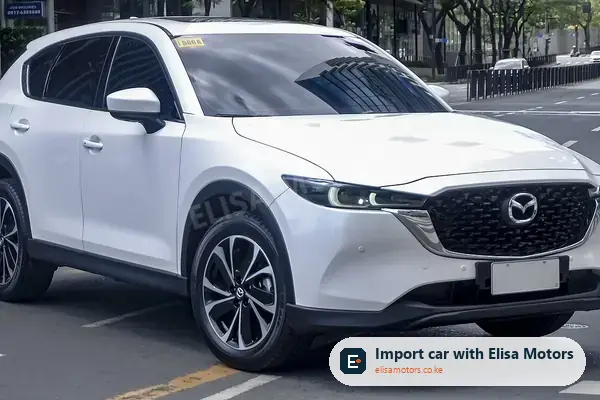
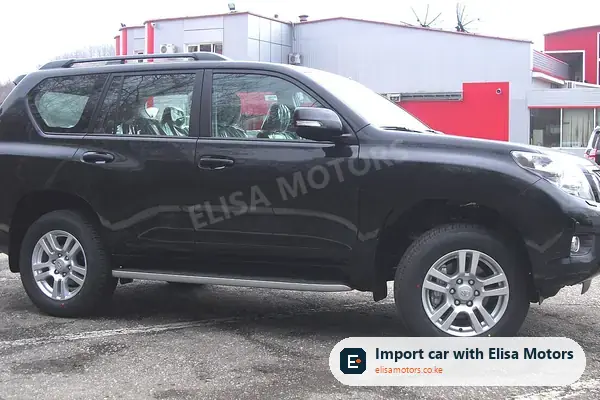
Crossovers are the easiest cars to finance. A Toyota Harrier Premium lands at about KES 4.3M – 4.9M. Likewise, a Mazda CX-5 20S lands at KES 2.8M – 3.2M, and a Prado TX at KES 6.2M – 7M. Banks know these models well, so approvals tend to be quick.
Buying a Japanese car on instalments directly from an exporter is rarely possible, because exporters want full payment before shipping. Instead, use a Kenyan bank or SACCO. That way, your money is protected by a regulated lender.
Logbook loans: when they make sense
A logbook loan uses a car you already own as security. The lender is added to the logbook, and you keep driving. Logbook loans are fast. However, they usually cost much more than bank asset finance. Moreover, missed payments can lead to repossession quickly.
So, should you use a logbook loan for a Range Rover, V8 or G-Wagon? Usually only as a short-term bridge, for example to fund a deposit while a bank loan is processed. For long-term financing, bank asset finance is almost always cheaper. Read the full cost, not just the monthly figure.
Comprehensive car insurance in Kenya
Kenyan law requires at least third-party cover. However, lenders require comprehensive cover, and almost every owner of a valuable car chooses it anyway. Comprehensive insurance covers accident damage, theft, fire and third-party claims.
Premiums are usually quoted as a percentage of the car's value, with a minimum premium. The rate depends on the insurer, the car, your driving history, where you park and whether the car has a tracker. Therefore, two quotes for the same car can differ a lot.
Range Rover insurance cost in Kenya
Range Rovers cost more to insure than many SUVs. Parts are expensive and theft risk is higher. Expect insurers to insist on an approved tracker. Read our Range Rover maintenance guide for running costs.
Toyota V8 comprehensive insurance
The V8 is a high-theft-risk car in Kenya. As a result, insurers require tracking and may require immobilisers or other security. In return, the car's strong value means claims are handled at realistic amounts.
G-Wagon comprehensive insurance cost
Because of its value, a G-Wagon has one of the highest premiums of any car in Kenya. Some insurers ask for secure parking and extra anti-theft devices. Shop around, and ask about excess levels.
Harrier, CX-5 and Prado insurance
Premiums for crossovers are more modest because values are lower. The Prado costs more to insure than a Harrier or CX-5, mainly due to theft risk. Moreover, CX-5 owners should ask whether side-mirror theft is covered, since mirrors are a common target in Nairobi.
How to lower your insurance premium
First, fit an approved tracking device and use secure parking. Second, choose a sensible excess. Third, keep a clean claims record, since no-claim discounts add up. Finally, compare quotes from several insurers or a good broker each year rather than renewing automatically.
Marine insurance while the car is shipping
Your car needs cover before it even reaches Kenya. Marine insurance protects it during shipping from Japan or the UK. We arrange it on every import. Then, comprehensive cover starts once the car is registered. Read our shipping guide for details.
Our services: finance-ready imports
1. Pro-forma invoices banks accept
We issue detailed pro-forma invoices with the full specification, chassis number and landed price in KSh.
2. Valuation support
We share photos, inspection reports and documents with your bank's valuer. As a result, valuation is fast.
3. Tracker fitting
We can fit an approved tracking device before handover, so your insurer and bank are satisfied from day one.
4. Insurance introductions
We can introduce you to insurers and brokers who cover imported luxury cars.
5. Clear timelines
We tell you and your bank exactly when the car will land, clear and register. Therefore, funds move at the right time.
Finance checklist
Before you sign, check the interest rate type (flat or reducing balance), all fees, the early repayment terms and the insurance requirements. Next, confirm the car's age fits the bank's rules for the full term. Finally, check that the car is 2019 or newer, so it can be imported in 2026. Read our car import scams guide to protect your deposit.
Talk to us
Call +254 725 310 112 or WhatsApp +254 725 310 112. Browse Prado, Harrier and Range Rover Sport prices, or send an import request.